⚡ Quick Summary
- HDFC charges zero prepayment fee on floating-rate home loans — fixed-rate loans may still have charges
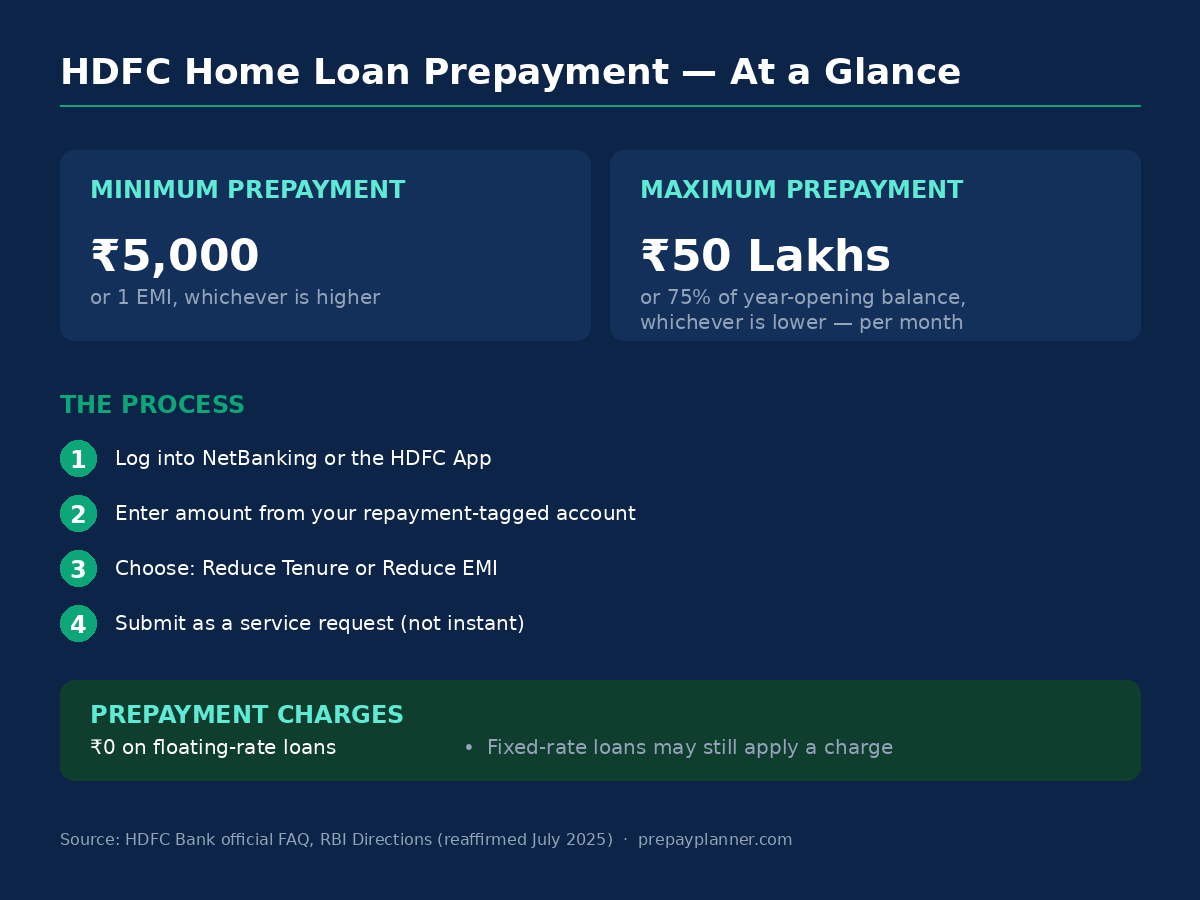
- Monthly prepayment limit: ₹5,000 minimum, up to ₹50 lakhs or 75% of your year-opening balance, whichever is lower
- You can prepay once per calendar month, only from your repayment-tagged bank account
- Prepayment goes through as a service request (NetBanking/App), not an instant transaction — plan a few days ahead
- Always explicitly choose tenure reduction over EMI reduction to save significantly more total interest
- PrepayPlanner shows your exact HDFC prepayment savings before you submit any request
In This Article
HDFC is the single most common lender across five of India's biggest home-loan markets — Bangalore, Mumbai, Gurgaon, Hyderabad, and Pune. If you're one of the millions of HDFC borrowers, the prepayment process has specific limits and steps that generic advice tends to skip. This guide covers exactly what applies to your HDFC loan.
Does HDFC Charge for Prepayment?
For floating-rate individual home loans — no. HDFC does not charge any prepayment or foreclosure fee, in line with RBI's directive that has applied since October 2012 and was reaffirmed in July 2025 with zero lock-in period as well, regardless of your loan's funding source.
Fixed-rate home loans are different — HDFC may still apply a prepayment charge on these. Most salaried borrowers are on floating-rate loans, but it's worth confirming your specific loan type before assuming zero charges apply.
Under RBI Directions reaffirmed July 2, 2025: banks cannot charge prepayment penalties on floating-rate individual home loans, and there's no minimum lock-in period before you're allowed to prepay. This is a universal banking rule, not an HDFC-specific policy — but it's exactly why floating-rate HDFC borrowers face zero friction on the charges side.
HDFC Home Loan Prepayment Limit
HDFC sets specific minimum and maximum limits on how much you can prepay in a single month:
| Limit | Amount |
|---|---|
| Minimum prepayment | ₹5,000, or 1 EMI — whichever is higher |
| Maximum prepayment | ₹50 lakhs per month, or 75% of your year-opening principal balance — whichever is lower |
| Frequency | Once per calendar month |
The source account matters too — HDFC only accepts prepayments from the specific bank account tagged to your loan repayment, not any account you choose. If you're planning a large bonus-season prepayment, confirm your funds are sitting in the correct linked account beforehand.
The Actual Online Process
HDFC offers what it calls "assisted digital part prepayment" — this is a genuinely online process, but it's worth understanding exactly how it works before you rely on it for time-sensitive prepayments.
If you'd rather not wait on digital processing, visiting your HDFC Home Loan Branch directly remains available for both partial and full prepayments, and can be faster for urgent, large, or full-closure prepayments specifically.
Common Mistakes HDFC Borrowers Make
Assuming the prepayment reflects instantly. Since this goes through as a service request, treating it like an instant NetBanking transfer can catch you off guard near financial year-end, when timing for tax purposes matters.
Prepaying from the wrong account. Funds sitting in a different savings account than the one tagged to your loan won't work — this trips up borrowers who maintain multiple accounts and don't always route their bonus into the correct one first.
Not checking loan type before assuming zero charges. Floating-rate is the norm for most salaried borrowers, but if you're on a fixed-rate HDFC loan, assuming the RBI zero-penalty rule applies to you specifically can lead to an unexpected charge.
Tenure Reduction vs EMI Reduction
When you submit your HDFC prepayment request, you'll be asked whether to reduce your EMI or reduce your tenure. This choice matters far more than most borrowers realize.
Reducing tenure keeps your EMI exactly the same but closes your loan earlier — eliminating entire months of future interest. Reducing EMI lowers your monthly payment but keeps the loan running for its full original term, meaning you keep paying interest for the same number of months, just less each time.
For the same prepayment amount, tenure reduction typically saves 2-3x more total interest than EMI reduction. Unless you have a genuine cash-flow reason to prefer a lower monthly payment, tenure reduction is almost always the stronger choice with HDFC specifically — and it's the option you have to actively select, not the one you can assume happens automatically.
City-Specific Notes
Bangalore: HDFC is the dominant lender here for IT professionals — with April and October bonus cycles, worth setting tenure reduction as your standing preference so you're not re-deciding with every prepayment request.
Mumbai: With HDFC loan sizes here often exceeding ₹80 lakhs, the ₹50-lakh monthly prepayment cap is genuinely relevant — large bonus-driven prepayments may need to be split across more than one calendar month to fully deploy.
Gurgaon: HDFC's strong corporate tie-ups with Gurgaon tech firms mean many borrowers here have HDFC loans through employer-linked programs — the standard prepayment process and limits above apply the same way regardless of how the loan originated.
Hyderabad: HDFC's dominance in the Hitec City and Financial District corridors means most local tech professionals are prepaying through exactly this process — worth bookmarking your NetBanking prepayment page for repeat use each bonus cycle.
Pune: With HDFC as the #1 lender for the Hinjewadi and Wakad IT corridor, and typically younger borrowers with longer remaining tenures, tenure reduction specifically captures the most value here — more years remaining means more interest eliminated per rupee prepaid.
You May Have Read Different Lock-In Periods — Here's the Current Answer
Search around and you'll find some articles citing a 12-EMI wait before HDFC allows prepayment, others mentioning 6 months. Both may have been accurate at some point, but they don't reflect the current rule: under RBI's directive, floating-rate individual home loans carry no minimum lock-in period at all. You can technically submit a prepayment request from your very first EMI onward. Older loan agreements or specific loan variants may have carried a waiting period in the past — but for a standard floating-rate HDFC home loan today, checking your own current sanction letter beats relying on either commonly-cited figure.
A Real Example — What This Looks Like in Numbers
Vikram, an operations lead in Gurgaon, took an HDFC home loan of ₹50 lakh at 9.1% for 18 years, with an EMI of ₹47,135. Four years in, he received a large ESOP payout and prepaid ₹7 lakh in one go, keeping his EMI unchanged and letting the tenure shrink instead.
| Without prepayment | With ₹7L prepayment at year 4 | |
|---|---|---|
| Total interest paid | ₹51,81,163 | ₹37,78,792 |
| Loan closes in | 18 years | 14.3 years |
The single ₹7 lakh prepayment saved him roughly ₹14 lakh in total interest and closed his loan nearly 4 years earlier — without changing his monthly EMI at all, and with zero fee since his loan was floating-rate.
How HDFC Compares to SBI and ICICI on Prepayment
The core prepayment rule is identical across all three — RBI's zero-penalty, floating-rate protection applies equally. Where HDFC stands apart is its specific monthly prepayment cap, which neither SBI nor ICICI impose in the same way:
| HDFC | SBI | ICICI | |
|---|---|---|---|
| Floating-rate prepayment charge | Zero | Zero (see our SBI guide) | Zero (see our ICICI guide) |
| Monthly prepayment cap | ₹50L or 75% of year-opening balance | No specified cap | No specified cap |
| Prepayment frequency | Once per calendar month | Unlimited | Unlimited |
If you're planning a very large, one-time prepayment, HDFC's monthly cap is the one genuine structural difference worth knowing about in advance — it may mean splitting a large bonus or windfall across two calendar months to fully deploy it, something SBI and ICICI borrowers don't need to plan around in the same way.
See your exact HDFC prepayment savings first
PrepayPlanner's free calculator shows your real interest savings before you submit any request to HDFC. The full Excel tool models tenure-reduction and EMI-reduction outcomes side by side, using your actual loan numbers. One-time purchase. Works offline.
Try Free Calculator → See Pricing from ₹199Frequently Asked Questions
Does HDFC charge for home loan prepayment?
No, for floating-rate individual home loans — HDFC does not charge any prepayment or foreclosure fee, consistent with RBI's directive effective since October 2012 and reaffirmed in July 2025. Fixed-rate home loans may still carry a prepayment charge, so always confirm your loan type first.
What is the minimum and maximum I can prepay with HDFC per month?
The minimum is ₹5,000 or one EMI amount, whichever is higher. The maximum is ₹50 lakhs per month, or 75% of your year-opening principal balance — whichever is lower. This limit resets each calendar month.
How do I prepay my HDFC home loan online?
HDFC offers assisted digital part prepayment — you raise a service request through NetBanking or the HDFC mobile app (Loan Section → Make a Prepayment), specifying the amount and payment method. Since this goes through as a service request rather than an instant transaction, processing can take a short time; visiting a Home Loan Branch remains an option if you prefer an immediate, in-person process.
Can I choose tenure reduction over EMI reduction with HDFC?
Yes — when you submit your prepayment request, you can specify whether you want your EMI reduced or your tenure shortened. Tenure reduction almost always saves significantly more total interest for the same prepayment amount, so it's worth explicitly selecting rather than accepting whatever HDFC defaults to.
How often can I prepay my HDFC home loan?
Once per calendar month, from the specific bank account tagged to your loan repayment. If you want to prepay more frequently than that, you would need to visit a branch directly to discuss your options.
This information is accurate as of August 10, 2026 and may change — always verify current terms directly with HDFC Bank. PrepayPlanner is an independent tool and is not affiliated with or endorsed by HDFC Bank.
This article is for educational purposes only. Consult a financial advisor or your lender directly for advice specific to your situation.