⚡ Quick Summary
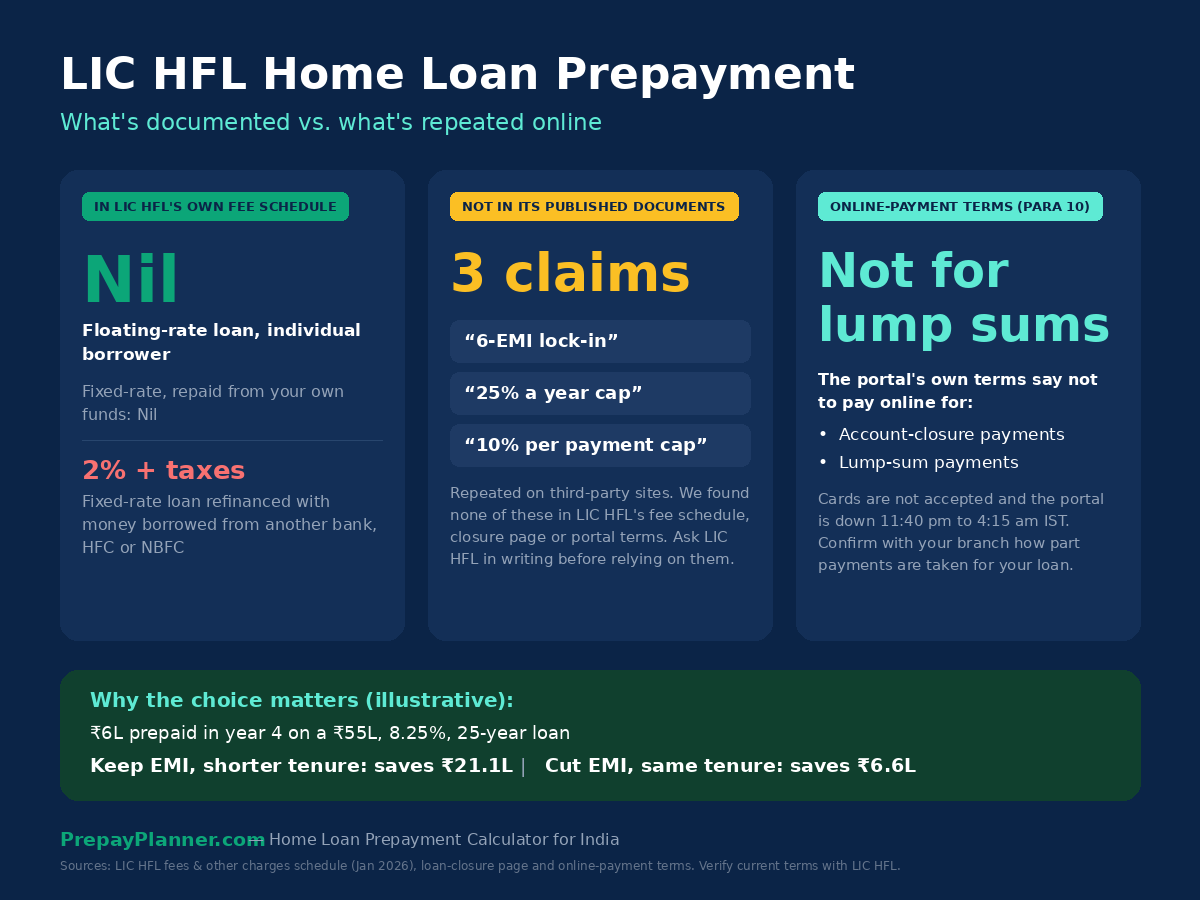
- LIC Housing Finance's own published fee schedule lists nil prepayment and foreclosure charges on floating-rate loans to individuals
- Fixed-rate loans are nil only if you repay from your own funds. Refinancing with another lender's money attracts 2% plus taxes
- The "6 EMIs lock-in" and "25% a year" limits quoted on other sites are not in LIC HFL's published documents. Confirm them in writing for your loan
- LIC HFL's online-payment terms say not to use the portal for lump-sum or account-closure payments, so plan how your part payment will actually reach LIC HFL
- In our worked example, keeping your EMI and shortening the tenure saved about 3x more than cutting the EMI
In This Article
LIC Housing Finance is one of India's largest home-loan lenders: ₹3.22 lakh crore of loans outstanding at June 30, 2026, of which about ₹2.72 lakh crore is individual home loans, according to its Q1 FY27 results. Yet search for how to prepay an LIC HFL loan and the answers contradict each other. One site says you must pay 6 EMIs first. Another says you can prepay at most 25% a year. A third gives step-by-step instructions for an "online prepayment tab".
This guide sticks to what LIC HFL has published and what RBI requires. Where we could not confirm a claim, we say so and tell you what to ask LIC HFL in writing.
LIC HFL Is Not LIC, and Not a Bank
LIC Housing Finance Limited (LIC HFL) is a housing finance company promoted by Life Insurance Corporation of India. It is a separate listed company: not a department of the insurer, and not a bank. That matters because your prepayment rules come from LIC HFL's own fee schedule and RBI's directions for non-bank lenders, and because you deal with LIC HFL's customer portal, branches and customer-care channels rather than a bank's net-banking app. That last point changes how a part payment actually reaches your loan account, as you'll see below.
Does LIC HFL Charge a Prepayment Penalty?
LIC HFL publishes a schedule of fees and other charges (the January 2026 version is on its website). For individual borrowers it says:
| Your loan | Prepayment / foreclosure charge |
|---|---|
| Floating-rate home loan, individual borrower | Nil |
| Fixed-rate home loan, individual, repaid from your own sources | Nil |
| Fixed-rate home loan, repaid from borrowed funds | 2% of principal prepaid + applicable taxes |
LIC HFL defines "own sources" as any source other than borrowing from a bank, housing finance company, NBFC or financial institution. Non-individual borrowers (such as companies) on floating-rate loans are charged 2% plus taxes, except micro and small enterprises. The schedule does not set a minimum prepayment amount or a separate part-payment charge.
Under RBI's Pre-payment Charges on Loans Directions, 2025, effective January 1, 2026, regulated lenders (including NBFCs, the category housing finance companies fall under) cannot charge prepayment penalties on floating-rate loans to individuals for non-business purposes. The rule applies irrespective of the source of funds and with no minimum lock-in period. It covers loans sanctioned or renewed on or after January 1, 2026. For older floating-rate loans, LIC HFL's own schedule already shows nil.
The Fixed-Rate Refinancing Trap
If your LIC HFL loan is fixed-rate, or you are not sure which type you have, the difference between "own funds" and "borrowed funds" decides everything.
Say you have ₹40 lakh outstanding on a fixed-rate LIC HFL loan and move it to another lender through a balance transfer. The repayment comes from another lender's money, so LIC HFL's schedule points to 2% of the principal prepaid plus taxes: ₹80,000 plus 18% GST, or ₹94,400. Prepaying the same loan from your savings or bonus: nil.
Two more charges from the same schedule matter if you are switching rate type within LIC HFL: a rewriting charge of ₹3,000 plus GST on individual housing loan schemes, and 0.25% of the outstanding amount plus GST to convert from floating to fixed. Before you pay any switching cost, run the numbers in our balance transfer vs prepayment guide.
The "6 EMIs", "25% a Year" and "10% Per Payment" Claims
Search results for LIC HFL prepayment are full of specific-sounding limits: pay 6 EMIs before you can prepay, prepay no more than 25% of the outstanding principal in a year, and no more than 10% in one payment. We looked for these where LIC HFL publishes its rules (the fees and charges schedule, the loan-closure page and the online-payment terms) and found none of them.
That does not prove no condition exists on your loan. Your sanction letter can carry terms that a public page does not. What we can say is this:
- For loans sanctioned or renewed on or after January 1, 2026, RBI's directions bar a minimum lock-in on floating-rate loans to individuals.
- LIC HFL's published schedule sets no minimum prepayment amount and no part-payment charge.
- For any loan, your sanction letter and LIC HFL's written reply outrank a blog post, including this one.
Ask LIC HFL these four questions in writing
Email customersupport@lichousing.com, or use the WhatsApp and helpline (1800 209 1989) numbers listed on lichousing.com, and keep the reply:
- Is my loan floating-rate or fixed-rate today?
- Is there any minimum or maximum part-payment amount, or any waiting period, on my loan?
- How do I make a part payment (branch cheque or demand draft, or online), and on what date will it be credited?
- After it is credited, will my EMI or my tenure change, and can you send me the revised repayment schedule?
How to Make a LIC HFL Part Payment (and Why the Portal May Refuse)
Many guides tell you to log in to the customer portal and open a "Prepayment" tab. LIC HFL's own online-payment terms (paragraph 10) list cases where you should not pay through the portal: when no due is overdue, when an ECS or PDC is in process, for account-closure payments, and for lump-sum payments. Card payments are not allowed, and the service is unavailable from 11:40 pm to 4:15 am IST.
Borrower reports differ. Some say a part payment went through the portal; others say the portal told them their loan was "not eligible for online payment" and sent them to a branch. These are anonymous forum posts, so treat them as a reason to ask, not as fact.
A Real Example — What This Looks Like in Numbers
Anand, a software engineer in Pune, has a ₹55 lakh floating-rate LIC HFL loan for 25 years at an illustrative 8.25% (your own rate depends on your profile and LIC HFL's current pricing). His EMI is ₹43,365. At the end of year 4 he puts a ₹6 lakh bonus into the loan. Same ₹6 lakh, very different outcomes:
| Total interest | Loan ends in | Interest saved | |
|---|---|---|---|
| No prepayment | ₹75,09,427 | 25 years | — |
| ₹6L at year 4, cut the EMI to ₹38,347 | ₹68,44,993 | 25 years | ₹6.6 lakh |
| ₹6L at year 12, keep the EMI | ₹65,61,888 | 22.1 years | ₹9.5 lakh |
| ₹6L at year 4, keep the EMI | ₹53,98,333 | 19.8 years | ₹21.1 lakh |
Keeping the EMI unchanged and letting the tenure shrink saves about ₹21.1 lakh and closes the loan about 5 years 2 months early. Cutting the EMI instead saves roughly a third as much. And waiting until year 12 to prepay the same amount cuts the saving by more than half. Savings are before tax and assume the rate stays constant; if LIC HFL's floating rate moves, actual figures move, but the order of the outcomes does not. For the reasoning, see Reduce EMI or Reduce Tenure? and the First 7 Years Rule.
Foreclosing Your LIC HFL Loan: Closure and Property Documents
LIC HFL's loan-closure page sets out several conditions that catch people out:
- Closure payments are accepted only from the applicant(s), not from third parties. Don't ask a relative to pay the closing amount directly.
- After closure, LIC HFL sends a system-generated message to your registered mobile number to schedule a document-collection appointment.
- Original property documents are handed over only if every applicant who is also an owner per the sale deed is present. Authorization letters are not accepted.
- Collect the documents within 10 days of the specified date. After that they go to the custodian, and retrieval can take 30 additional days.
RBI's rule on releasing property documents also applies to NBFCs and housing finance companies: original documents must be released and registered charges removed within 30 days of full repayment, with compensation of ₹5,000 per day for delays attributable to the lender (for cases falling due on or after December 1, 2023). Note the date of your closing payment, and book the collection appointment as soon as the message arrives.
How LIC HFL Compares to the Banks
The zero-charge principle for floating-rate loans to individuals is the same at SBI, HDFC, ICICI and PNB. What differs is the mechanics, and as a housing finance company LIC HFL's lump-sum process, "own funds" test and closure rules are its own.
Common Mistakes LIC HFL Borrowers Make
Assuming a fixed-rate loan behaves like a floating-rate one when refinancing. The "own funds" test is what separates nil from 2% plus taxes.
Following "online prepayment" steps from a blog. LIC HFL's own terms list lump-sum payments among the cases not to pay through the portal. Ask first.
Sending a relative, or an authorization letter, at closure. Payments must come from the applicant(s), and every owner-applicant must be present to collect documents.
See what your own LIC HFL prepayment is worth, tax impact included
PrepayPlanner's free calculator shows your real savings from your own loan numbers. The full Excel tool tracks your Section 24(b) safe limit automatically, whichever lender you borrow from. One-time purchase. Works offline.
Try Free Calculator → See Pricing from ₹199Frequently Asked Questions
Does LIC HFL charge a prepayment penalty on home loans?
For floating-rate home loans to individuals, LIC HFL's published fee schedule lists the prepayment and foreclosure charge as nil. For fixed-rate loans to individuals it is nil if you repay from your own funds, and 2% of the principal prepaid plus applicable taxes if the money comes from borrowing from a bank, housing finance company, NBFC or financial institution.
Is there a 6-EMI lock-in on LIC HFL home loans?
Some third-party websites say you must pay 6 EMIs before you can prepay. We could not find such a rule in LIC HFL's published fee schedule, loan-closure page or online-payment terms. For loans sanctioned or renewed on or after January 1, 2026, RBI's directions bar any minimum lock-in on floating-rate loans to individuals. Because your sanction letter governs your own loan, confirm in writing with LIC HFL.
Is there a 25% per year limit on LIC HFL part payments?
Some sites cite a cap of 25% of outstanding principal per year and 10% per payment. Neither limit appears in LIC HFL's published fee schedule, which sets no minimum prepayment amount and no separate part-payment charge. Ask LIC HFL whether any limit is written into your own sanction letter before you plan around one.
Can I prepay my LIC HFL home loan online?
LIC HFL's customer-portal payment terms say not to pay online for account-closure payments or lump-sum payments, and card payments are not accepted. Some borrowers report the portal accepting part payments on their accounts while others are told to visit a branch, so ask LIC HFL which channel applies to your loan (customer care 1800 209 1989 or customersupport@lichousing.com).
Will a part payment reduce my EMI or my tenure at LIC HFL?
That depends on the option LIC HFL applies to your account, and we could not verify a default, so ask for the one you want in writing. In our worked example (₹55 lakh, 8.25%, 25 years, ₹6 lakh prepaid after year 4), keeping the EMI and shortening the tenure saved about ₹21.1 lakh in interest, against about ₹6.6 lakh for cutting the EMI.
What does it cost to move a fixed-rate LIC HFL loan to another lender?
Per LIC HFL's fee schedule, a fixed-rate loan repaid with borrowed money attracts 2% of the principal prepaid plus applicable taxes. On ₹40 lakh outstanding that is ₹80,000 plus 18% GST, or ₹94,400. A floating-rate individual loan shows a nil charge, which changes the balance-transfer maths completely.
How long does LIC HFL take to return my property documents after closure?
RBI requires regulated lenders, including NBFCs and housing finance companies, to release original property documents and remove registered charges within 30 days of full repayment, with compensation of ₹5,000 per day for delays attributable to the lender. LIC HFL says it sends an SMS to schedule a collection appointment, asks you to collect within 10 days of the specified date, and needs every applicant who owns the property to be present.
Is LIC HFL the same as LIC of India?
No. LIC Housing Finance Limited is a separate listed housing finance company promoted by Life Insurance Corporation of India. Your home loan agreement is with LIC HFL, not with the insurer, and LIC HFL is not a bank.
This information is accurate as of October 7, 2026 and may change — always verify current terms directly with LIC Housing Finance Limited. PrepayPlanner is an independent tool and is not affiliated with or endorsed by LIC Housing Finance Limited or Life Insurance Corporation of India.
This article is for educational purposes only. Consult a financial advisor or your lender directly for advice specific to your situation.